Every business that sells online depends on one piece of infrastructure most customers never think about: the payment gateway sitting behind the checkout button. Get it wrong and you lose sales to failed transactions, unsupported payment methods, or a checkout page that spooks first-time buyers. Get it right and the payment gateway technology becomes one of the quieter drivers of revenue growth, especially once it enables your business to start selling into markets your original setup was never built for.
Growing a business online, whether you run an eCommerce store or operate in financial services, depends on choosing payment gateway technology that can flex with you. Technology designed for one market rarely holds up in the next one, especially once local compliance and regulatory requirements enter the picture, which is exactly why the choice matters as you expand into regions where your current setup starts showing its limits.
Key takeaways:
A payment gateway is the technology layer that captures, encrypts, and routes payment data so a transaction can be approved or declined.
The technology works alongside a payment processor, which is the separate service that moves funds between banks.
Gateways come in several forms, hosted, integrated, API-based, in-person, and mobile, each suited to a different kind of business.
Choosing the right one affects your approval rates, your checkout experience, and ultimately how much revenue reaches your account, particularly if you sell into markets where local payment methods matter more than cards.
Table of contents
What Is a Payment Gateway?
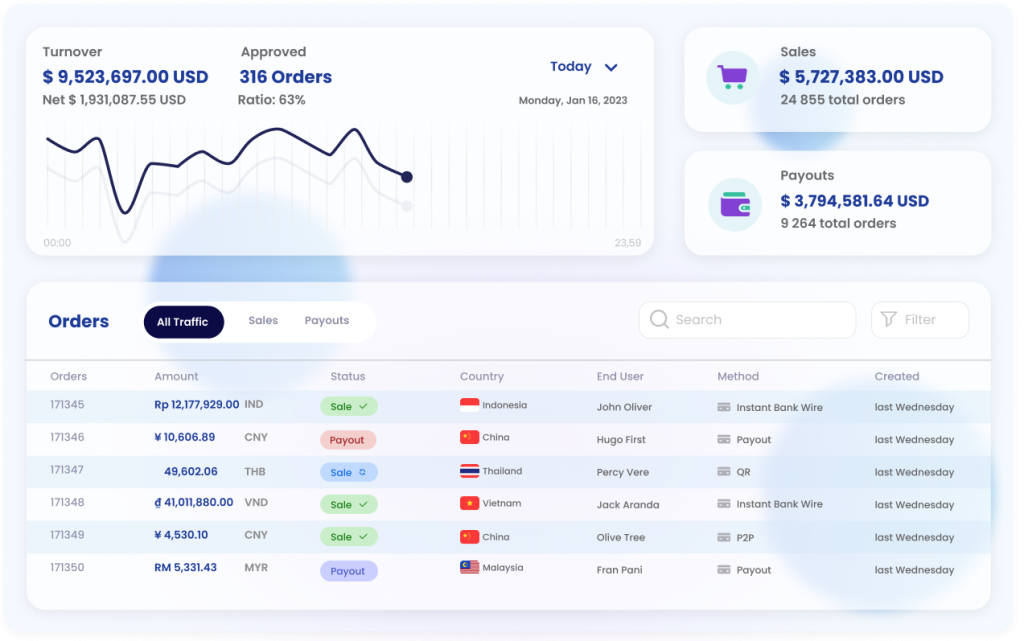
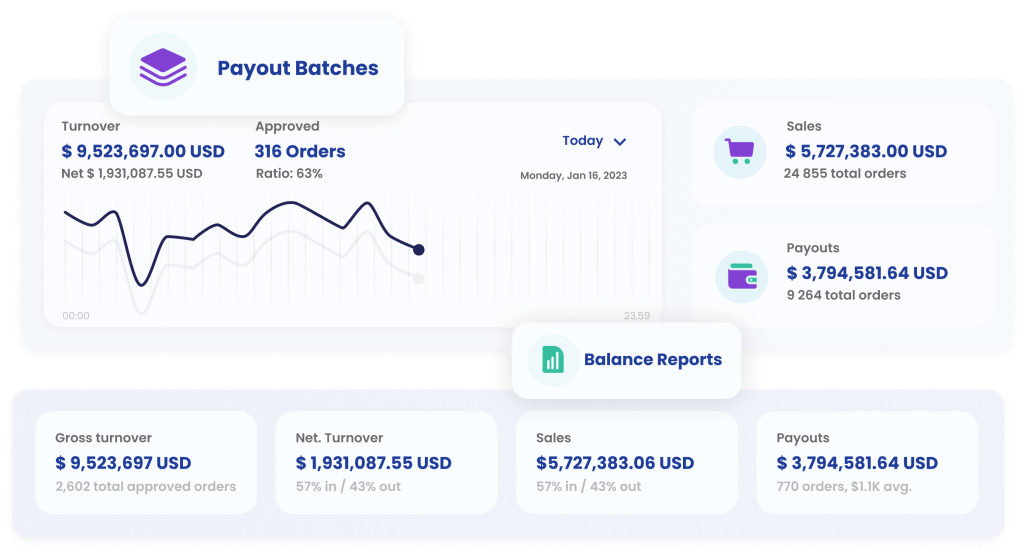
Payment gateway technology is a digital infrastructure that enables online businesses to connect to alternative payment methods globally through a unified API. This technology enables payment solutions like digital wallets and QR codes, allowing international businesses to route transactions efficiently across premium, high-risk, and underserved emerging markets.
In practice, Zota’s own payment gateway technology, the Metagate™, a B2B payment gateway technology, enables connections of a business’s website or app to the banks, eWallets, and local payment networks’ customers rely on. The technology enables bank transfers, digital wallets, and hundreds of alternative payment methods, routing each transaction to wherever it needs to go for approval while meeting the compliance requirements specific to that market. Getting this wrong carries real consequences: transactions can get blocked, regulators can impose fines, and banking partners can pull support altogether, so compliance sits at the center of the technology rather than as an afterthought bolted on. Well-built payment gateway technology also secures sensitive user information throughout that journey, so customers get a checkout that feels quick and trustworthy rather than one that makes them second-guess handing over their details.
Payment gateway technologies open up a new world of opportunities for global businesses, equipping them with the tools to sell their products across the globe and accept payments in any local currency. The global market for payment gateways is growing, hitting 58.8 billion in 2026, but expected to rise to 245 billion by 2033.
How Does Payment Gateway Technology Work?
Payment gateway technology executes six steps within seconds to process a transaction. The process begins with customer payment initiation, followed by immediate data encryption by the gateway. The gateway then communicates data to the processor, the issuing bank authorizes the transaction, the gateway displays approval or decline, and the processor completes final fund settlement.
Step 1: Payment Initiation
The customer enters their payment details, or selects a digital wallet, at checkout. This is the only part of the process the customer sees.
Step 2: Encryption
The gateway immediately encrypts that data before it goes anywhere else. Nobody along the chain, not even the client’s own servers in most setups, sees the raw card or account number.
Step 3: Communication with the Payment Processor
The gateway passes the encrypted data to a payment processor, the separate service responsible for moving money between banks. This is a useful distinction to hold onto: Zota’s payment gateway technology operates at the gateway layer, enabling businesses to connect to the processing and banking partners that complete a transaction.
Step 4: Bank Authorization
The processor forwards the request to the customer’s issuing bank, which checks the account for available funds and confirms the transaction looks legitimate.
Step 5: Transaction Approval or Decline
The bank sends its decision back through the same chain. The gateway receives it and tells the checkout page whether to show a success message or ask the customer to try again.
Step 6: Settlement Overview
Approved funds don’t land in the client’s account instantly. They move through a settlement process, usually completed within a day or two, where the processor batches and transfers the money to the business’s account.
What are the Key Functions of a Payment Gateway?
A gateway does more than pass data back and forth. Four functions matter most.
First, every payment detail gets encrypted the moment it enters the system, protecting it from interception as it travels between the customer, the business, and the banks involved.
Building on that foundation, modern gateways also screen transactions in real time, flagging patterns that look suspicious before a fraudulent charge goes through to protect both the business and the customer in the process.
Underpinning all of this is compliance: handling card data means meeting the Payment Card Industry Data Security Standard (PCI DSS), a set of security requirements that gateways build into their infrastructure so clients don’t have to build it themselves.
And for higher-risk transactions, extra verification steps like 3D Secure add a further layer of identity confirmation, reducing chargebacks without adding much friction for legitimate customers.
What are the Different Types of Payment Gateways?
Five main types of payment gateways accommodate different business needs. Integrated gateways maintain checkout on the business website, while hosted gateways redirect customers to a provider’s secure page. API-based gateways allow custom integration, in-person terminals handle face-to-face transactions, and mobile gateways optimize in-app purchases for smaller screens.
Integrated Gateways
The entire checkout stays on the business’s own site or app. Customers never leave to complete payment, which gives businesses full control over branding and the checkout experience, at the cost of taking on more responsibility for security.
Hosted Gateways
The customer gets redirected to a secure page run by the payment provider, completes the transaction there, and returns to the client’s site afterward. This shifts more of the security burden onto the provider, which smaller teams often prefer.
API-Based Gateways
Developers connect directly to the gateway’s API, building a fully custom checkout experience. This gives the most flexibility and is the approach behind Zota’s single-API model, where one integration enables a business to connect to over a thousand local payment methods rather than requiring separate builds for each one.
In-Person Payment Terminals
Physical card readers and point-of-sale devices apply the same gateway logic to face-to-face transactions, whether that’s a countertop terminal or a mobile card reader.
Mobile Payment Gateways
Built specifically for in-app purchases and mobile checkout flows, these gateways account for smaller screens, mobile wallets, and the payment habits that dominate mobile-first markets.
Alternative Payment Methods
Alternative payment methods (APMs) refer to non-traditional payment methods, such as eWallets, bank transfers, and mobile money. They are the ideal solution for customers who don’t want to use credit/debit cards or other conventional payment methods when transacting online or sending money to friends or family. APMs have become more and more popular in recent years and by 2029, 69% of global eCommerce transactions are forecasted to be made through APMs. Knowing what APMs to offer customers is part of the vital process that every business needs to go through when setting up their online business.
Payment Gateway vs. Payment Processor
The main difference between payment gateways and payment processors is their role in the transaction. A payment gateway securely captures and transmits payment data from the customer to the client’s business. A payment processor routes that data between the business’s bank and the issuing bank to authorize and settle the transaction.
Neither works without the other. A gateway with no processor to hand data to cannot complete a transaction, and a processor with no gateway has no way to receive that data in the first place.
Any business selling online needs both pieces working together, whether that comes from two separate vendors or one provider offering both under a single integration. What matters more than the label is whether the combination gets a transaction from checkout to settled funds reliably, across every market you sell into.
Payment Gateways and Merchant Accounts
For established online companies looking to expand into emerging markets, it can seem overwhelming. That’s why it’s vital for them to understand the various digital payment services at their disposal and how to tailor-make their eCommerce site to accommodate as wide a range of payment needs as possible. While payment gateways facilitate charging customers’ preferred payment method, merchant accounts enable businesses to accept such payments online. Any company wanting to process transactions needs to apply for a merchant account, but it’s crucial to have that account with a reputable and experienced company.
What are the Benefits of Using a Payment Gateway?
Encryption and fraud screening reduce the odds of a breach reaching sensitive customer data, and that same fraud screening pays off again at checkout, catching suspicious activity in real time before it becomes a chargeback and protecting revenue that would otherwise get eaten up by disputes.
Security aside, the checkout experience itself matters just as much. A fast, reliable checkout keeps customers from abandoning their cart at the last step, which happens more often than businesses realize when payment options feel limited or transactions run slowly. Supporting the payment methods customers already trust removes one of the most common reasons a sale falls through, and on the back end, most authorization decisions come back within seconds, keeping the checkout experience feeling instant rather than uncertain.
Presenting the payment flow in the customer’s own language and currency, with the local alternative payment methods they actually recognize and can use, makes the whole experience feel familiar rather than foreign, which keeps customers moving through checkout instead of second-guessing it.
Payment Gateway Technology for High-Risk and Emerging-Market Businesses
Most mainstream gateways get built for low-risk industries selling in developed markets, and it shows. Try running a forex platform or an online trading platform through a gateway designed for mainstream retail, and you’ll hit declined applications, capped transaction limits, or approval rates that quietly cost you revenue every month.
The same gap shows up geographically. In markets where card penetration is low, a gateway that only supports Visa and Mastercard misses a large share of potential customers outright. Businesses expanding into these regions need a gateway built around the payment methods people there use, from mobile money to local bank transfers, alongside payment gateway technology built for the approval ratio requirements.
Conclusion
A payment gateway is the technology that makes every online transaction possible, and choosing the right one affects far more than checkout speed. It shapes which customers you can serve, how many transactions get approved, and how much revenue reaches your account instead of disappearing into declines and abandoned carts.
Zota enables the connection of online businesses to over a thousand local payment methods through the Metagate™ single API. Every lead and every live client brings a different set of requirements and goals, so Zota tailors the solution to each business rather than fitting clients into a fixed package. If your current gateway technology is holding back growth in the markets you’re trying to reach, get in touch with Zota’s team to talk through what a better fit looks like.
FAQs
Can I Build My Own Payment Gateway?
Technically, yes, but most businesses underestimate what that actually takes. You’d need to meet PCI DSS requirements on your own, build fraud infrastructure, and maintain all of it as rules and threats keep shifting. The heavier cost shows up once you expand past one region. Going it alone means connecting to a different provider for every country and payment method you want on your checkout page, and each one comes with its own underwriting, its own onboarding, its own integration to build and maintain separately. Add a new market and you’re back through that whole process again.
With Zota, that work happens once. A single integration through the Metagate™ API enables payment methods across every region and country Zota supports, so growing into a new market means switching on the relevant methods rather than starting from scratch.
Why is it Important to Choose a Well-Established Gateway Technology Provider like Zota?
Zota has spent over a decade building a payment gateway technology and the regional relationships that come with it, working directly with local banking partners and alternative payment providers across emerging markets. That experience means the compliance frameworks and risk infrastructure behind every transaction have already been tested and refined, not built on the fly.
Those long-standing relationships translate into steadier approval rates and fewer disruptions for businesses enabling payment solutions in new regions. As a marketplace of payments purpose-built for high-risk industries and underserved markets, Zota brings the licensing groundwork, banking connections, and regional expertise that make expanding into emerging markets smoother from day one.
What Is the Difference Between a Payment Gateway and a Payment Processor?
A gateway captures and encrypts payment data, then routes it toward approval. A processor is the separate piece that moves the money itself, settling funds between the customer’s bank and the business’s bank. Zota builds the payment gateway technology. The company connects businesses to the processing and banking partners a transaction needs, rather than handling the fund movement itself.
How Does a Payment Gateway Protect Customer Data?
The moment a customer enters their details, the gateway encrypts them, so raw account numbers never travel unprotected between the customer, the business, and the banks in between. Good gateway technology also screens transactions as they happen, catching patterns that look off before they turn into fraud. Compliance work like PCI DSS gets built into that infrastructure from the start, and for riskier transactions, an extra step like 3D Secure confirms identity without slowing the customer down much.
What Are Alternative Payment Methods and Why Do They Matter?
Alternative payment methods, or APMs, cover everything outside the card networks: eWallets, bank transfers, mobile money, QR codes. A business that only enables Visa and Mastercard shuts out customers across huge parts of the world, especially in markets where cards never became the default way people pay.
Why Do High-Risk Businesses Need Specialist Gateway Technology?
Most gateways get built with low-risk retail in mind, and a forex platform or trading business running through one of those hits declined applications and capped limits fast. Specialist gateway technology gets built around the risk profile those industries actually carry. Zota positions itself as a marketplace of payments , connecting businesses to alternative payment methods and banking partners so the focus stays on APM coverage and approval ratios for emerging-market businesses.
Why Does Zota Use Gateway Technology Instead of Operating as a Direct PSP?
Acting as a direct processor means owning the banking relationships, the settlement infrastructure, and the regulatory licensing in every market a client operates in. Zota’s marketplace of payments model works differently: the company connects businesses to the network of processing and banking partners that already exist in each region, through one API. A business gets the coverage without either side rebuilding infrastructure market by market.
Do You Need to Re-Integrate Every Time You Add a New Country?
No. One integration with Metagate™ connects a business to the local payment methods across every market Zota supports. Adding a country usually means switching on the relevant payment methods for that region inside the existing setup, not building a new connection from the ground up.
What Determines Payment Gateway Technology Approval Rates?
Approval rates come down to fit. A gateway needs fraud screening tuned to the actual risk profile of the business, coverage of the payment methods customers in that market already use, and banking partnerships willing to work with higher-risk transaction volumes. Generic gateways built for low-risk retail tend to produce weaker approval rates for a forex or trading business, since none of that infrastructure was designed with those transactions in mind.
Disclaimer
This blog is for marketing and informational purposes only. Zota’s services are designed exclusively for businesses, with availability varying by jurisdiction, local laws, and our Terms of use.
Nothing published here constitutes an offer, guarantee, or financial advice. Zota’s security and compliance tools complement, rather than replace, your internal controls. You retain sole responsibility for meeting your legal and regulatory requirements.