Table of Contents
Online businesses that want to reach customers across different regions need to match how those customers prefer to pay. One of the biggest shifts in global commerce has been the rise of eWallets, digital tools that let consumers store funds, manage finances, and complete transactions from their devices. In emerging markets especially, where traditional banking infrastructure remains thin, eWallets have grown in popularity over recent years.
Let’s explore what eWallets are, their benefits for online businesses, and how they work with payment gateway technology to support global commerce.
What is an eWallet?
An eWallet is a secure digital application that stores payment credentials and funds. It allows users to execute electronic transactions using a smartphone or computer. This technology replaces physical payment cards by facilitating instant online purchases and contactless terminal transactions through encrypted data transmissions.
You will see the terms “eWallet,” “digital wallet,” and “mobile wallet” used almost interchangeably in everyday conversation. They overlap, but they are not identical. A digital wallet is the broadest category, covering any software that stores payment credentials. A mobile wallet is the subset designed for smartphones and wearables, focused on contactless in-store payments. An eWallet often carries its own stored balance, functioning more like a virtual version of the leather wallet in your pocket. For the purposes of this article, we use “eWallet” as the general term because it best captures the range of functionality businesses encounter when expanding into new payment regions.
In emerging markets, where banking access is often limited and approval processes for traditional accounts can be slow, eWallets give underbanked populations an accessible and practical financial tool. That matters for any business looking to serve customers in Southeast Asia, Latin America, Africa, or the Middle East.
How Do eWallets Work?
The surface experience of paying with an eWallet feels simple: open an app, confirm a purchase, and move on. Behind that seamless experience, several technologies work together to enable fast, secure transactions – helping businesses deliver a smoother checkout while protecting sensitive payment data.
When customers set up an eWallet, they link a funding source and complete a quick verification process. The wallet then encrypts payment details and uses secure tokens instead of exposing sensitive card information. Payments are processed through technologies such as NFC, QR codes, or direct online integrations, enabling businesses to offer customers a fast, secure, and frictionless checkout experience.
How eWallets Work with Payment Gateway Technology
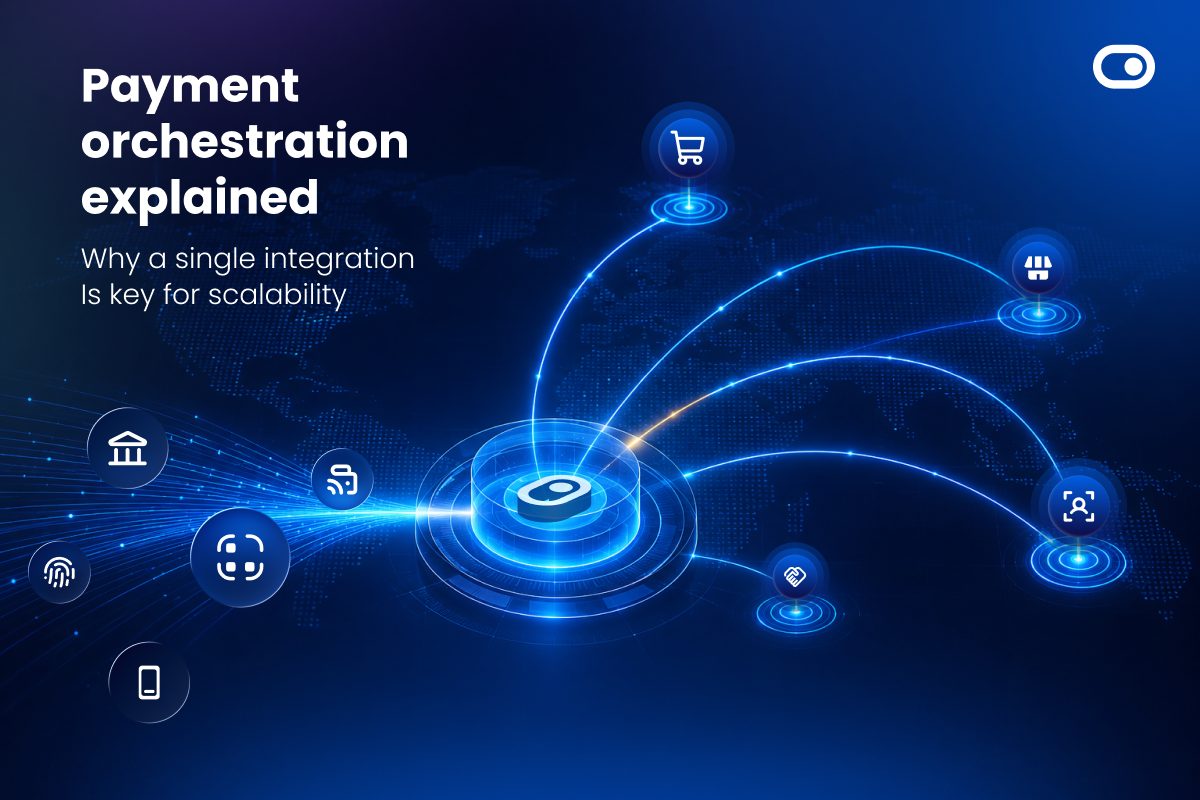
The eWallet handles the customer-facing side of a transaction. Payment gateway technology handles everything behind it. The platform sits between the eWallet provider and your business platform, routing the transaction, verifying the funds, and returning a confirmation. Without it, you would need to build and maintain a direct integration with every eWallet provider in every market you serve.
A strong payment gateway technology setup gives you four things that matter when you are working with eWallets at scale.
Integration With Multiple eWallet Providers
Rather than building separate technical links to each wallet in each country, your gateway connects you to all of them through one API. If your customers in Thailand prefer PromptPay while your customers in Brazil prefer Pix, you cover both without doubling your development work.
Real-Time Transaction Processing
The gateway technology routes funds between the eWallet and your platform in seconds, which keeps your cash flow moving and your customers from waiting.
Multi-Currency Support
Your customers pay in the local currency they trust while you settle in the currency you need. The gateway handles the conversion so you do not have to manage exchange rates or build currency logic into your own systems, which reduces conversion fees and removes a source of friction that can kill a sale.
Regulatory Compliance
Every country has its own rules around payment processing, data handling, and financial reporting. Payment gateway technology absorbs that complexity and keeps your cross-border operations running within the legal requirements of each region, so you can focus on growing rather than on reading local financial regulations.
For businesses expanding into emerging markets where eWallet adoption is high and customer preferences vary from country to country, this combination of broad wallet coverage, real-time processing, multi-currency support, and built-in compliance is what makes the difference between a smooth rollout and a fragmented, resource-heavy one.
What are the Benefits of eWallets for online businesses
As online businesses seek to expand globally, offering eWallet payment options has become crucial to catering to diverse customer preferences. But why are eWallets essential for online businesses?
Increased customer reach
Many customers, especially in developing regions, prefer using eWallets over traditional banking methods due to their convenience and accessibility. Enabling eWallet payments allows businesses to tap into new markets and demographics.
Enhanced security and fraud protection
eWallets use advanced encryption and tokenization technologies to protect customer data, reducing the risk of fraud and unauthorized access. They often incorporate multi-factor authentication, increasing security for both customers and businesses.
Boosting financial inclusion
eWallets provide an entry point into the digital economy for unbanked and underbanked populations. Businesses that support eWallet payments can foster greater financial inclusion and build trust with customers who lack access to formal banking services.
Convenience and speed
eWallet transactions are fast and frictionless, enabling customers to complete purchases with just a few taps. This streamlined checkout experience reduces cart abandonment rates and increases customer satisfaction.
Mobile-First Approach
Customers can make purchases anytime, anywhere, without needing to enter lengthy payment details. This matters most in markets where a smartphone is the primary way people access the internet. An eWallet removes any barriers entirely, letting a purchase happen in the same handful of taps a customer already uses to send a message or check a balance.
Lower Transaction Costs
Many eWallet providers offer competitive transaction fees compared to traditional financial institutions, making them a cost-effective solution for businesses looking to expand into new markets without absorbing the higher processing costs that often come with cross-border card payments.
Is it Safe to Use an eWallet for Online Transactions?
The short answer is yes. Modern eWallets are designed with multiple layers of security that help protect both consumers and merchants throughout the payment process.
Rather than sharing a customer’s actual card or account number, eWallets use tokenization to replace sensitive payment details with secure, single-use tokens. Even if intercepted, these tokens cannot be reused or traced back to the original payment credentials.
Most eWallets also require biometric or device-based authentication before a payment is approved, adding an extra layer of protection against unauthorized transactions. Combined with encryption and built-in fraud prevention measures, this helps reduce payment risk while giving customers greater confidence at checkout.
For merchants, these security features translate into safer transactions, lower exposure to payment fraud, and a more trusted checkout experience that can improve customer confidence and conversion.
Limitations of eWallets
No payment method is perfect, and being upfront about the trade-offs builds credibility with the businesses and consumers you are trying to reach.
Device Dependency
For your customers, an eWallet lives on a device. If that device runs out of battery, breaks, or gets left at home, they lose access to their funds until they can get back to it. A physical wallet does not need charging, and in regions with unreliable power infrastructure, many end users keep a backup payment method available for this reason. From your side as a merchant, this is a customer-level friction point, not a reason to hold back on offering eWallets. If eWallets are a preferred payment method in the markets you operate in, your checkout needs to support them. Customers who reach for their eWallet and find it at checkout convert. Customers who don’t see it leave.
Merchant Acceptance
eWallet coverage varies by region and by provider. A wallet that works at every store in Bangkok may be unrecognized in Lagos. This fragmentation is one of the biggest challenges for businesses expanding across multiple emerging markets, and it is also one of the reasons a broad alternative payment method strategy matters. Partnering with a payment gateway technology provider that connects your business to multiple eWallets through a single integration helps you avoid the need to build separate integrations for each wallet in each country.
Implementing eWallets in Your Business
eWallets are transforming the global payment landscape, offering online businesses a secure, convenient, and inclusive way to accept global payments online. As digital adoption continues to rise, businesses that leverage payment gateway technology to support eWallets can unlock new growth opportunities and stay ahead of the competition.
For businesses looking to implement eWallet payments, choosing reliable payment gateway technology that supports a wide range of eWallet options is essential. Zota’s technology is connected to more than a thousand global eWallets and other alternative payment methods. Our secure platform can be customized to meet your unique business needs; with one simple API integration, you can select the payment methods that are most popular in your target regions to cater to the preferences of local consumers.
Want to learn more about how Zota can support your business growth? Get in touch with our team of payment experts!
FAQs
1. How do I know which eWallets are popular in the market I’m operating in or planning to enter?
eWallets provide a digital alternativPayment preferences shift from one country to the next, and what works in one market can be irrelevant a border away. A shopper in Nairobi reaches for mobile money, someone in Manila pays through GCash, and in São Paulo your customers expect Pix-linked options at checkout. Zota has spent over a decade mapping these preferences across emerging markets, building relationships with local payment providers and tracking which methods gain traction in each region. That experience sits behind a payments marketplace connecting you to more than a thousand alternative payment methods through a single API, so you enable the eWallets and APMs your customers prefer without building a separate integration every time you expand into a new country.
e to physical cards by securely storing payment details on a mobile device or cloud platform. They offer faster transactions, enhanced security, and often additional features such as loyalty rewards and budgeting tools.
2. Can eWallets support cross-border transactions?
Yes, many eWallets support cross-border transactions, allowing businesses to accept payments in multiple currencies. Payment gateway technology provides this by converting currencies and maintaining compliance with local financial regulations.
3. What are the costs associated with accepting eWallet payments?
The costs vary depending on the eWallet provider and region but are often lower than traditional banking fees. Many businesses find eWallets a cost-effective solution due to their lower transaction fees and reduced chargeback rates.
4. Can eWallets support financial services industries like forex and trading?
eWallets can absolutely support high-risk industries like forex and trading, and in plenty of cases they work out better than traditional cards. Forex brokers often run into higher decline rates and tighter card scheme scrutiny, while eWallet rails tend to carry fewer restrictions around funding sources and settle with less friction.
5. Are eWallets subject to chargebacks and payment disputes?
Since eWallets pull from pre-loaded balances or linked accounts rather than running through a card network, there’s usually no card network standing behind a dispute the way there is with a traditional card transaction. Disputes can still happen through the eWallet provider itself, but the volume and cost businesses face tend to drop noticeably once eWallets make up a bigger slice of the transaction mix.
Disclaimer
This blog is for marketing and informational purposes only. Zota’s services are designed exclusively for businesses, with availability varying by jurisdiction, local laws, and our Terms of use.
Nothing published here constitutes an offer, guarantee, or financial advice. Zota’s security and compliance tools complement, rather than replace, your internal controls. You remain solely responsible for meeting your legal and regulatory requirements.